The Real Scoop on US Health Care
Last week I was getting my hair cut – I do have enough left to make it worthwhile – and the lovely lady who does that for me got to talking about the fact her adult son was headed off to a new job in the US of A. This worried her, and one particular worry she had was whether he would have health insurance. He had assured her that the company that had lured him south was taking care of all that, and I have no doubt that is true. It’s a big corporation, and most of those still have insurance plans for their employees, and pretty good ones.
However, in the course of this chat, my hair cutter said something like – ‘You know, in the States some 40% of people have no health insurance. They just have to go bankrupt if they get really sick or injured.’
That 40% made my spidey-sense tingle, as in ‘Surely that’s not correct’. I didn’t say anything at the time, believing it is a bad idea to argue with someone who is holding a sharp object near your neck, and besides – I didn’t really know that statistic was wrong. It just seemed too high to me.
I have no idea where she got that number, but it seemed to me to be the kind of no-evidence factoid that people throw around who wish to maintain a belief that health care in the US is a nightmare, and in particular much worse than in Canada.
Well, the US health care system is indeed a big mess, but so is the Canadian one – they are just different kinds of messes. And I have a pre-disposition against incorrect facts, so I left with my hair shorter and a determination to see if I could find out what the actual number is.
Here is what I found out, but I start by saying where I found it. It comes from a website belonging to a non-profit org called KFF, which used to stand for Kaiser Family Foundation. In fact it is no longer a foundation (since 2019) and the IRS classifies it as a public charity.
KFF was set up back in the 40s by industrialist Henry Kaiser, who also founded Kaiser Permanante, which is today the largest private, health care provider in the US. It operates hospitals and provides health care insurance, mostly in the western US.
My predisposition is to mistrust any info on health care that comes from a large org within the US health care industry. However, so far as I can tell, KFF By 1985 no longer had an ownership stake in the Kaiser companies and was no longer associated with Kaiser Permanente, or the Kaiser Industries. It is now, it says on its website, a research and information non-profit which relies on donations to operate. You can check out the Board of Trustees here for yourself, for whatever that is worth.
Being naturally suspicious, I went looking for signs that KFF is biased or untrustworthy. I found a site called ‘Media Bias Fact Check’ which said that KFF was ‘moderately left of centre’ and ‘highly factual’. That would be more reassuring if I knew something more about the reliability of Media Fact Check Bias, but I don’t. I also, however, found a story written by people at KFF in which the headline was: Deloitte’s Medicaid Systems Are Wrongly Denying Disabled Americans Benefits in at Least 25 States, KFF Investigation Finds, dated last July.
That does not look to me like a story written by people in an org that is doing propaganda for the private health care providers in the US.
So, I am going to take the data below as being as accurate as data on something as complex as this can be. You can decide for yourself how much faith to put in it.
The KFF site has no paywall, so you can check out all this data yourself here, if you like. I will start with this direct quote from the KFF website.
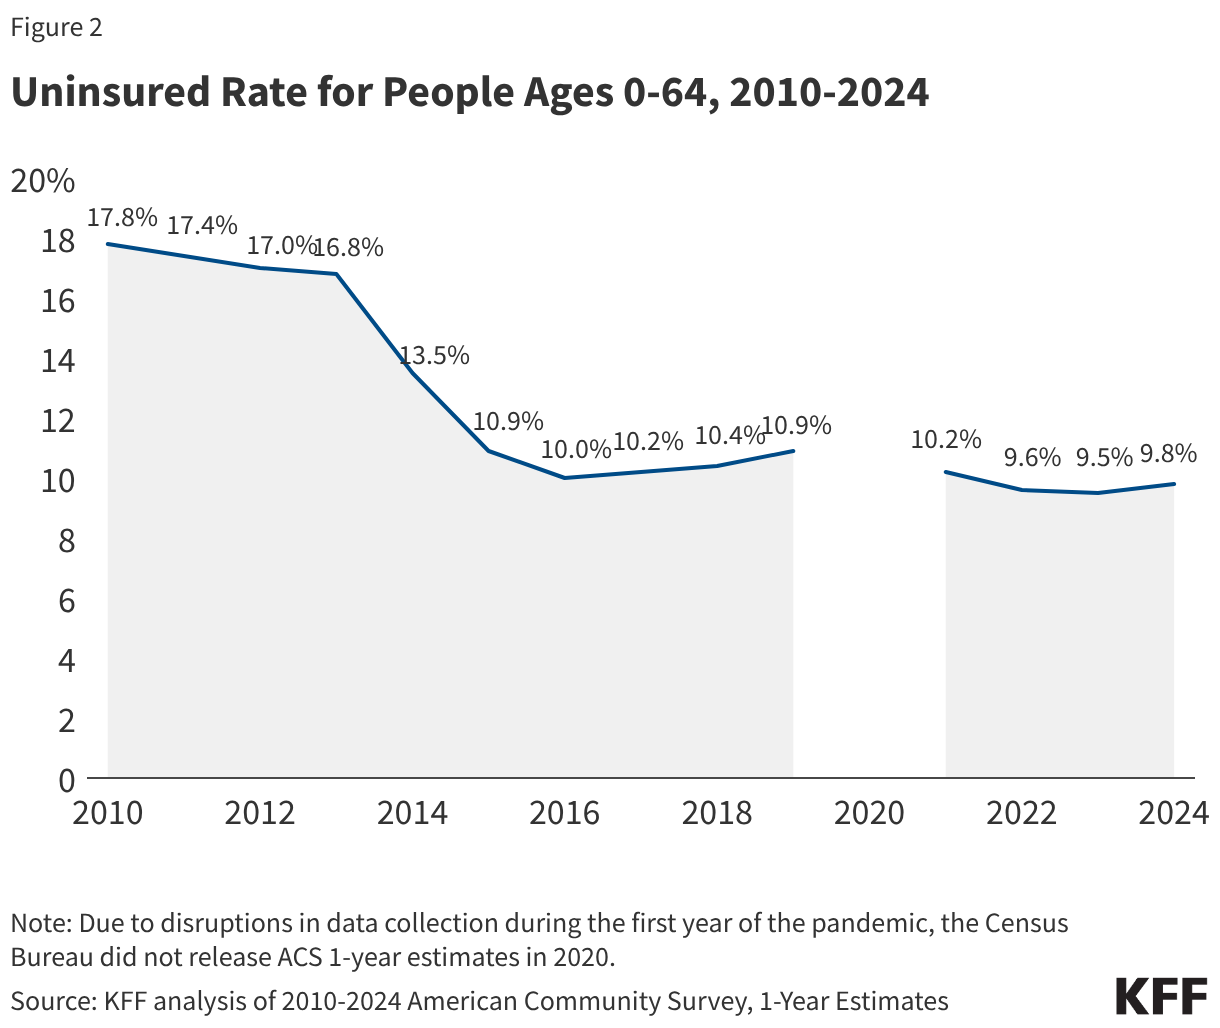
For the first time since 2019, the number of people without health coverage and the uninsured rate increased in 2024. The total number of people ages 0-64 without health coverage increased by more than 1.3 million to 26.7 million in 2024, and the uninsured rate for the population under age 65 increased from 9.5% to 9.8%.
I should note that the most current numbers on the site are for 2024, that seems to be the most recent data they have. Note also that the numbers are for those under 65, as 65 and older folks are automatically covered by a government program known in the US as Medicare.
So, note that the number of uninsured below age 65 has increased, as well as the percentage of that population. However, note also what that percentage is – 9.8%.
That is a very long way from 40%. Hell, it’s a long way from 20%.
Now, the insured numbers in the US have tended to jump around a lot, and as far as I can tell this has been because US politicians insist on tinkering with the way Medicare, Medicaid (for the poor) and so-called Obama-care work. Endlessly.
Here is a graph from the site showing how things have varied since 2010:
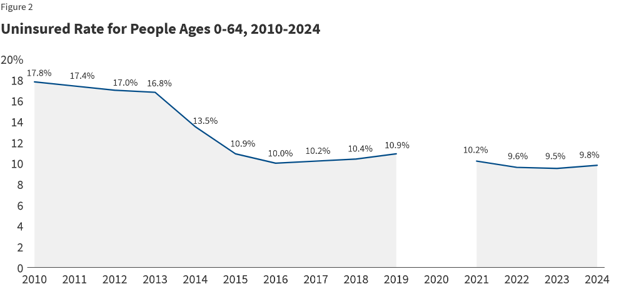
So, the uninsured rate’s clear trend over time has been downward. The uptick from ’23 to ’24 is a so-far one-off. Note that it happened before The Orange Guy took office for the second time, but that the previous years in which the rate increased were between 2016 and 2019, his first term.
I further note that on the KFF site, at the bottom of that graph above, it says:
Source: KFF analysis of 2010-2024 American Community Survey, 1-Year Estimates Get the data Download PNG
The ACS is a real thing, although I cannot of course vouch for KFF’s analysis of the data. It is none the less a very good sign that you can get the data yourself if you have doubts. That says ‘credible’ to me.
When Obama Care was first passed, it was a time of great joy for health economists, as they had the birth of a whole new system to study. One of the facts that even a non-health economist like myself heard bandied about was that a big share of those without insurance were young adults. If you were in your 20s and healthy, and your employer did not provide health insurance, you might very well decide to skip buying any, since the chance you would need it was rather low.
Whether or not you think that is wise, and I suspect many Canadians are appalled by the very notion, the KFF data suggests this remains true. Here’s another graph depicting the proportion of uninsured among the various age groups up to age 64:
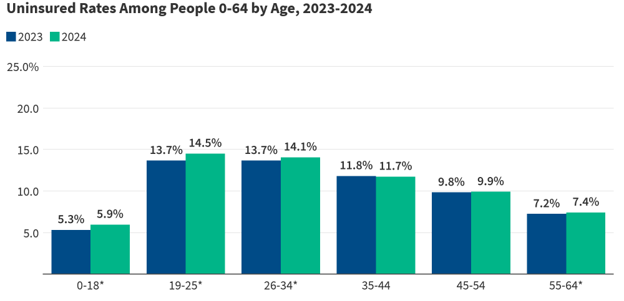
After age 19, people are more likely to get insured as they get older.
So, as I suspected, the number quoted by my hair cutter was way off the mark.Of course, being insured in the US is not like having the Canadian version of health insurance. Even the best US insurance involves some deductibles and possibly some level of co-payment. I, for one, think that is a good thing.
As I noted, my stylist also spoke as though going bankrupt due to medical bills is pretty common in the US.
I went to look into that, also, but here ran into a bigger problem. Not of data, but of concept. What does it mean to have a bankruptcy ‘caused’ by medical expenses? Here is a very useful synopsis of the issue from one source on this I read:
Researchers disagree on the evidence for medical bills causing bankruptcies. The biggest problem in answering this question is that those filing for bankruptcy aren’t required to state the reason.
As a result, estimates are based on surveys. Therefore, the answer will depend on how researchers phrase their questions, and how the survey respondents define the cause of their bankruptcy.
A variety of factors cause bankruptcies. Many people with medical debt have other debts as well. They may also have a lower income, little savings, or have lost a job.
You can read this whole piece here if you like. Again, no paywall. Among other things it points out the widely differing estimates of the frequency of medical bankruptcy arrived at in different surveys. It seems to matter a lot how the question is asked, as is typical.
In short, I don’t know what to think of this second claim, as no good data seems to be available. I will end with a last bit of dubious data, none the less. The site World Population Review, not one I generally have much faith in, reports what are the top four countries in terms of the percentage of total personal bankruptcies that are caused by medical bills. Now, be clear about what this statistic means. In each country, people who went bankrupt were asked what caused that bankruptcy. The percentage who said ‘medical bills’ in each country are listed below:
USA 66.5%
Canada 19%
Australia 10%
UK 8.2%
These data, such as they are, leave more questions unanswered than answered. What is the proportion of the population in each place that suffers a bankruptcy for any reason each year? How do the consequences of a bankruptcy differ in each country? What is the most-cited cause of bankruptcy in the countries other than the US?
So many good questions, but I am out of answers for now.